Structural versus Cyclical: What Matters More?
Economic Transformation Meets the Business Cycle

Anirban Basu is the Chairman & CEO of Sage Policy Group and Chief Economist of the Modular Building Institute.
Leo Tolstoy’s acclaimed novel Anna Karenina opens with the famous line, “All happy families are alike; each unhappy family is unhappy in its own way.” Something similar can be said for the various segments that comprise the U.S. construction industry. Those segments that have dominated construction spending growth in recent years share a common feature – they benefit from dramatic economic transformations that generate a need to significantly alter the built environment. By contrast, segments that have not prospered generally have category-specific reasons for their malaise.
There are several structural transformations impacting the U.S. economy that stand to drive construction spending higher even if interest rates stay elevated for longer and the economy enters a mild recession. At the top of that list is construction related to manufacturing. For decades, supply chains were relocated from America to a bevy of nations offering lower wages, more relaxed regulatory environments, investment in supporting infrastructure, and rapidly expanding industrial workforces. The mantra among many American manufacturing CEOs appears to have been that as a profit maximizing enterprise, one must also be a cost minimizer, and minimizing costs means manufacturing beyond American boundaries.
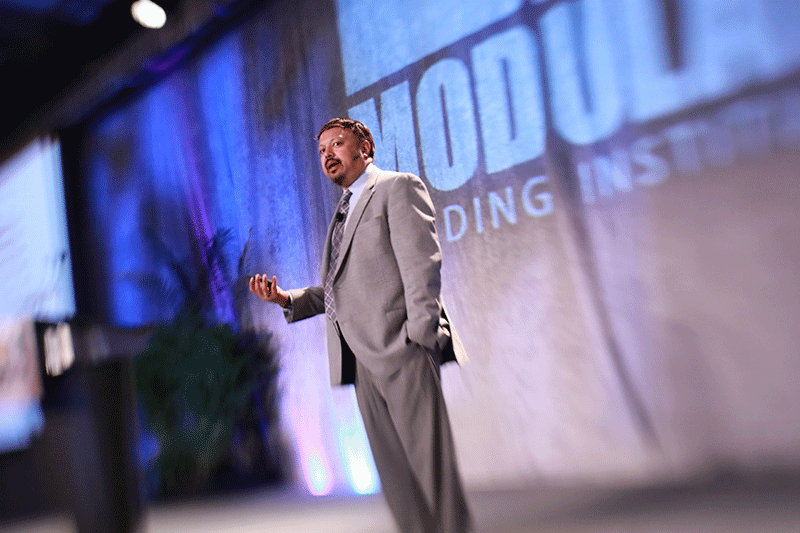
Anirban Basu speaks at the Modular Building Institute's annual World of Modular conference.
But now a new set of considerations have induced leaders of major global manufacturing enterprises to reconsider their site selection decisions. Among these are:
- a desire for simpler logistics emphasizing shorter transit distances and times;
- a need to better protect intellectual property;
- more reliable court systems;
- incentives offered by the USMCA, America’s trade deal with Canada and Mexico; and
- a recent set of subsidies offered under packages like the Chips and Science Act and the Inflation Reduction Act.
What’s more, certain advantages offered by other nations have been diminished by time. As indicated by Deloitte analysts, labor cost pressures in the U.S. and Western Europe “are being mitigated by advances in robotics and automation.” Meanwhile, Chinese wages have been ramping higher, increasing 83 percent over the past decade.
The impact on the U.S. construction industry has been nothing short of mind-bending. Between February 2020 and November 2023, total nonresidential construction spending in America expanded 29 percent (not adjusting for inflation). Meanwhile, construction spending in the manufacturing segment grew 168 percent.
Importantly, this is not a cyclical phenomenon. In fact, by one prominent measure (the Institute for Supply Management’s Purchasing Managers Index), the U.S. manufacturing sector had been in recession for 14 consecutive months through December 2023. Nonetheless, manufacturing related construction volumes have continued to edge skyward as structural factors predominate.
Structural factors are impacting several other segments as well. Among them are data centers, driven in part by the growing pervasiveness of artificial intelligence, healthcare facilities, supported by an aging population and rising healthcare utilization, and infrastructure, promoted by an abundance of federal support spawning from legislation passed in 2021.
According to CBRE, data center supply in primary markets expanded by nearly 492 megawatts or 12 percent during the first half of 2023 compared to the latter half of 2022. On a year-over-year basis, supply expanded by 19 percent. More data centers are on the way. According to the same source, “an all-time high of 2,287.6 MW was under construction in primary markets”, representing a 25 percent year-over-year increase.
For modular builders and other industry stakeholders, these structural dynamics are of consequence, or at least they should be. For the better part of two years, contractors and others involved in interest rate sensitive economic segments have fretted about the impact of higher rates and possible recession. At the time of this writing, interest rates are still high despite expectations that the Federal Reserve will begin to loosen monetary policy later in 2024 and in 2025. Risk of recession remains. But the structural transformations transpiring in the economy signify that some construction segments stand to continue to expand even if the U.S. economy enters a period of downturn at some point this year or next.
There are, of course, some real estate and construction segments that are negatively impacted by structural changes. Among these changes are the specter of remote work, business meetings conducted on various online platforms, and e-commerce. While e-commerce has helped spawn an industrial space boom in America as Amazon and others have developed a need for additional fulfillment center space, demand for shopping center space has been compromised. During the 1980s there were around 2,500 mall locations in America. By the early parts of the current decade, that figure had declined to around 700. A Wall Street Journal article quoted expert Nick Egelanian, president of retail consulting firm Site Works, who indicated that roughly a decade from now that figure could be down to 150. Such trends have obvious implications for retail construction.
Hotels catering to business travelers have also been impacted by newly emerging behaviors. Conducting business meetings, including the delivery of economic forecast presentations, via online platforms has become far more common. While leisure travel came back with a vengeance during the pandemic recovery period, business travel did not. Not coincidentally, among nonresidential construction’s sixteen segments, no segment has experienced as much spending decline as lodging.
And then there is the office market. This is a market that has also been negatively impacted by structural changes, and tends to suffer greatly during periods of recession. Despite U.S. economic and employment growth last year, the national office vacancy rate continued to rise. As lease renewals continue over the next several years, vacancy stands to climb. There is also a debt maturity wall, meaning that many building owners will have to refinance their debt into higher interest debt during the years ahead. In many instances, building owners are likely to hand their keys over to the bank as building valuations slip below balances owed. Among other things, that will translate into more difficult project financing for office space developers.
In the final analysis, modular builders will want to align themselves with relevant economic segments that stand to benefit from structural economic shifts. There are a few of them set to create prospective opportunities for contractors to support deal flow even if the broader economy enters its next downturn at some point in the near-term.
More from Modular Advantage
Mind the Gap: The Interface Between Onsite and Offsite Construction
Every design for manufacture and assembly (DfMA) project — modular, mass timber, or panelized — is really two projects joined at a seam. One is built in a controlled factory to millimeter tolerances; the other in the field, in weather, to the looser tolerances of poured concrete and human hands. Between them sits an interface: where the factory’s precision meets the site’s reality.
Rules, Rails & Repeatability: Applying DfMA to Modular Healthcare
DfMA offers several advantages for healthcare projects, with faster delivery among the most valuable. Schedule matters when building new facilities, expanding campuses, renovating existing space or bringing care closer to communities that need it.
Precision and Possibility: Demands of DfMA and What Modular Mass Timber Makes Possible
Mass timber does not automatically create an efficient modular building. Its precision makes early coordination more important: fabricated components will accurately reproduce both the team’s solutions and its mistakes. The material’s advantages are realized only when supported by an equally precise design and delivery process.
Catch It in the Factory, Not in the Field: Smarter Testing for Modular Builds
Integrating watertightness and airtightness testing into factory workflows transforms quality assurance from a reactive process into a proactive commissioning strategy. It ensures that every module shipped is field ready and resilient for transportation while also supporting the ability of the modular construction industry to make buildings better.
Modular Construction Contracts: Key Considerations for Successful Canadian Projects
Starting a modular project with a well-developed contract protects both the owner and the contractor. It will help keep the project on track and on budget, and it will improve quality from the factory floor to final installation on-site.
Modular by Design: Turning Architecture into a Manufacturing System
Modular construction is often presented as a faster way to build. Speed, however, is only one part of its value. The larger opportunity is to create a coordinated design and production system that improves quality, reduces uncertainty, and allows a building to move efficiently from concept design through manufacturing, transportation, installation, and completion.
Repeatability Begins with Trust: What Alora at Dry Creek Reveals About Scaling Modular Housing
Alora at Dry Creek, a 329-unit, multifamily community comprising five four-story buildings in Centennial, Colorado, demonstrates how repeatable design, standardized manufacturing and early collaboration can work together to create a model that is not only faster to deliver, but easier to replicate across future projects.
T.R. Arnold: The Art of Third-Party Inspections
T.R. Arnold (TRA), a third-party inspection company in Elkhart, Indiana, contracts with modular manufacturers across the US. Manufacturers register with each state to which they intend to send their modules and may be required to hire a third-party inspection company.
Creating an ‘Ecosystem for Innovation:’ 50+ Years of Modular Construction Oversight in Virginia
Virginia’s modular building program began in 1973, with the implementation of the Virginia Industrialized Building Unit and Mobile Home Safety Regulations. Now it’s leading the country in modular code adoption.
Understanding Thermal Barriers Compliance Methods & Emerging NFPA-275 Foam Plastic Technologies
New fire barrier technologies are improving total costs and margins in major areas of construction, such as commercial, government, union and prevailing wage projects. These benefits translate into other large fringe areas, such as agriculture, commercial cold storage facilities, grow houses, outbuildings, military and aviation hangars.