
Is the World Deglobalizing?
A new report from Anirban Basu, chairman & CEO of Sage Policy Group and Chief Economist of the Modular Building Institute

Anirban Basu is chairman & CEO of Sage Policy Group and Chief Economist of the Modular Building Institute
International Trade Matters as Much as Ever
There is a popular narrative indicating that the world is now splintering after a period of coming together. For decades, the world seemed destined to become a unified production unit. Dozens of free trade agreements, the expansion of World Trade Organization (WTO) membership, and import/export data suggested that national boundaries were falling, at least with respect to the movement of goods, including productive construction inputs.
According to the World Trade Organization’s Regional Trade Agreements Database, there are nearly 600 trade agreements in force around the world. The most common are free trade agreements between nations, but many also go so far as to support economic integration. The U.S. is party to 14 such agreements, including bilateral agreements with the Republic of Korea, Israel, and Chile. But the most important of these agreements is the US-Mexico-Canada agreement or USMCA.
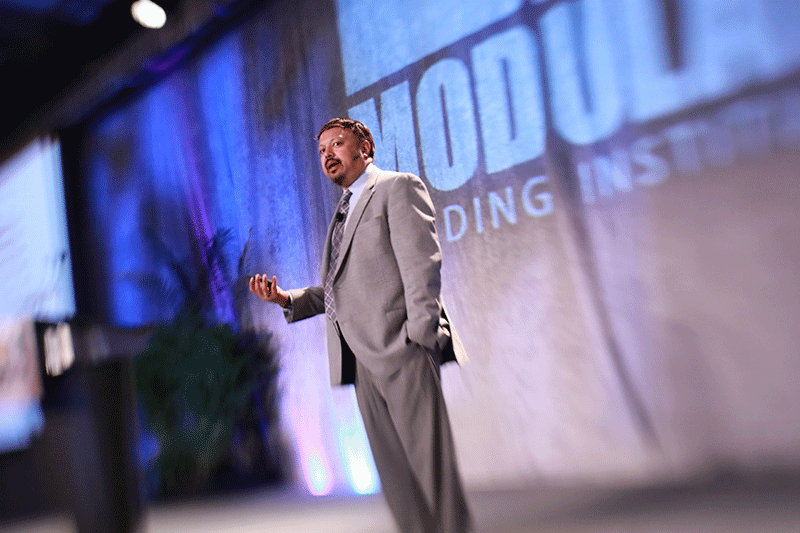
Anirban Basu speaks at MBI's annual World of Modular conference and tradeshow.
Despite trade wars and other forms of conflict, the value of global merchandise trade expanded 12 percent last year to US$ 25.3 trillion, inflated in part by elevated global commodity prices. WTO economists have estimated that merchandise trade volume growth will approach 2 percent this year and then rebound to 3.2 percent in 2024. In short, global trade remains a massive and global force. For MBI members, this means that global supply chains and their degree of functioning will continue to matter even as America seeks to restore various supply chains, including those related to computer chip and battery production.
The Current State of Global Supply Chains
As of this writing, the conflict in Ukraine enters its 17th month. With fighting spilling into Russia, the U.S. and its allies pledging additional military and financial aid to Ukraine, the impacts of the war can be felt everywhere and are spreading, but most particularly in Europe.
An interesting implication has been the further elevation of the importance of natural gas. Economic sanctions placed on Russia by the U.S. among others have forced the balance of Europe to turn to alternative energy sources. Enter liquefied natural gas (LNG). According to Glenn Rickson of S&P Global Commodity Insights, “[Natural gas] is like oil in that it’s now a global commodity via LNG and has a much higher geopolitical significance because of the events of the past year”. He added, “It is also now arguably a higher value product than oil.”
With Covid disrupting supply chains and a war in Eastern Europe following hot on its heals, it comes as no surprise that global supply chains were massively disrupted. As vaccines became widely available in the U.S. and the economy reopened in fits and starts, consumer demand surged. As indicated by the Council on Foreign Relations, “at the same time, companies in critical sectors such as warehousing struggled to attract and retail workers.
These factors, combined with years of underinvestment in U.S. infrastructure, saw goods-laden containers piling up at major ports and ships waiting for weeks to dock.”
It appears that late-2021 represented the worst for such issues. Since then, supply chains have been in recovery mode, helping to drive down many costs, including energy and other construction input costs. The New York Fed’s Global Supply Chain Pressure Index (GSCPI) indicates that in May global supply chains experienced the least pressure of any month since the start of the data series in 1997 (though the GSCPI did increase slightly in June).
Freight rate data coincide with this finding. International container rates have declined 88 percent since their peak in late 2021 according to the Freightos Baltic Index. North American truck freight rates are down more than 10 percent over the past year according to the Cass Freight Index. All things being equal, such dynamics support construction industry profitability, including within its modular building segment.
International Manufacturing
Supply chain functioning is set to improve over the next several quarters, but this has little if anything to do with supply. Weakening demand for goods in the U.S. and elsewhere will generate less pressure on manufacturers and distributors, helping to speed up delivery times.
According to S&P Global data and the Institute for Supply Management (ISM), America’s manufacturing sector is contracting in the context of rising inventory levels. A CNN report from June noted that the U.S. manufacturing sector contracted in May according to S&P Global data. ISM data indicate that the industry has been contracting for seven months. Durable goods orders have been rising in recent months, however, in large measure because of the volatile transportation sector.
In Europe, recent economic numbers point to recession for the continent’s largest economies. Reuters reported in late-July that both French and German economies are contracting. High interest rates promulgated by the European Central Bank have waylaid consumers and diminished economy activity. A Purchasing Managers’ Index covering the euro zone indicates that manufacturing activity contracted in July at its fastest pace since Covid.
And then there’s China. Global factory activity continues to slump according to many private surveys, with economists increasingly concluding that slowing growth and broadening economic weakness in China are taking a toll on the global economy. As reported by Reuters, S&P Global’s gauge of worldwide manufacturing activity stood at 48.7 in July, matching its lowest level since June 2020 when Covid was still undoing international commerce. The subindices of factory output and new orders both slipped to six month lows.
Looking Ahead
After enjoying a period of robust demand for their output, many manufacturers around the world are struggling to generate orders. Not only will that place downward pressure on prices, it will induce faster delivery times, including for input-purchasing modular builders.
At the same time, America is rebuilding critical supply chains, eventually expanding domestic production and simplifying logistics. Many of the headlines focus on the reshoring of electronics and inputs to alternative energy. Nonetheless, the trend toward reshoring is more general in nature, and should help modular builders more easily source key inputs, including sustainable timber.
At the same time, certain construction segments that tend to utilize modular building services frequently enjoy solid prospects, including single-family homebuilding, education, and healthcare. While certain key commercial real estate segments may exhibit profound weakness and risk of recession remains elevated, at this point, based on supply and demand fundamentals, the outlook for modular building appears solid.
More from Modular Advantage
From Model to Machine: Why Modular Scale Is Becoming a Software Problem, not a Material One
For modular manufacturers that have already secured demand and repeatable volume, the next major constraint may no longer be forming capacity itself. Increasingly, it is the continuity of the information feeding that capacity.
Who Will Define Modular Products for AI?
Artificial intelligence is making building configurators easier and less expensive to create. This makes urgent manufacturers’ need portable product definitions, stable identities, and shared interfaces regardless of how others’ software is produced.
From BIM to Robotic Production: A Digital Workflow for Customized Components in Volumetric Modular Construction
For volumetric modular manufacturers, the value of this workflow is not simply the use of robotics. Its real value is continuity.
Helping Build a Common Framework for Modular Construction in Canada
Canada’s modular construction sector continues to gain momentum, but scaling it successfully will depend on shared expectations across design, manufacturing, approvals, and project delivery. CSA Z251 helps provide that common foundation.
Edges, Exits & Equipment: A Modular Builder’s Guide to Rooftop Access
Rooftop access belongs in the factory design. Before the modules ship, the project team should identify each route’s users, confirm applicable requirements, coordinate with the roof system and structure, and assign responsibility.
When Timber Production and Modular Construction Share One System
As demand for multifamily and workforce housing continues to outpace what conventional construction timelines can deliver, models that reduce the number of handoffs between structural fabrication and modular assembly are likely to draw more attention.
Your AI Strategy Is an Enablement Strategy
Tools will change. Teaching employees only the steps in one platform creates a narrow capability. Involving them in problem definition, process mapping, data assessment, controls, and measurement gives the organization a way to improve its systems as technology evolves.
By-Right Permitting: The Missing Lever for Scaling Modular Multifamily
Modular has already proven it can outperform traditional building methods on speed and cost per unit. The next frontier is outside the factory in the front end of the process, where projects either clear a path to construction or get stuck in review.
Remote Inspections and The Future of Factory Oversight
Remote inspection is becoming a practical part of modular construction oversight. Its value is greatest when it is used selectively, governed by clear procedures, and supported by complete traceability.
Reimagining Dry-In: How a Temporary-to-Permanent Roofing Strategy Mitigates Risk Between Modular Installation and Final Roof Construction
As volumetric modular projects continue to increase in scale and complexity, the Temporary-to-Permanent FiberTite Roof System represents an example of how traditional trade scopes can be reimagined through Design for Manufacturing and Assembly (DfMA) principles.