
America’s Construction Economy: A Race Against Time
Anirban Basu is Chairman & CEO of Sage Policy Group and Chief Economist of the Modular Building Institute.
The Landing is Still Soft
The ongoing strength of the U.S. economy has been a source of incredulity for many economists. When interest rates took off in 2022, a conventional wisdom formed indicating that America was headed for certain recession in 2023. Economists from Bloomberg and elsewhere placed the probability of an economic downturn last year at or near 100 percent. That had everything to do with rising interest rates, which not only caused many stock values to tumble in 2022, but also implied a weakening of both consumer and business spending in 2023.
But no downturn came. Instead, the U.S. economy managed to grow 2.5 percent. Job growth continued, wage pressures persisted, consumers kept spending and travelers kept traveling. Meanwhile, inflationary pressures abated as something akin to pre-pandemic normalcy began to take hold.
While it remains easy to point to many challenges, including in the forms of war, Red Sea piracy, and unpredictable elections transpiring in much of the world, U.S. economic growth has continued apace. According to an initial estimate from the U.S. Bureau of Economic Analysis, the economy expanded at a 2.8 percent annualized rate during 2024’s second quarter. A separate report from the Federal Reserve Bank of Atlanta indicates that the U.S. economy is poised to roughly match that performance during the third quarter.
At the heart of America’s momentum, which has generally not been matched in the balance of the advanced world, has been a consumer who has been willing to ramp up their indebtedness to continue spending. While surging credit card debt and expanding delinquency represent causes for concern, they also reflect an underlying confidence in the future. Much of this confidence is attributable to labor market performances that continue to exceed expectations. An initial estimate from the U.S. Bureau of Labor Statistics indicates that America added another 206,000 in June, which means that national employment is up by 6.3 million since February 2020, the month before the pandemic undid the economy.
While it is true that unemployment has continued to edge higher, standing at 4.1 percent in June, that remains reasonably low by historic standards. A rising unemployment rate is also consistent with diminishing wage pressure, another prominent feature of the U.S. economy. That declining wage pressure along with sharp declines in the price of many goods (though not services) has positioned the Federal Reserve to begin reducing interest rates in September. The prospect of declining interest rates has many economic stakeholders abuzz with hope, something reflected in record stock prices as reflected in many indices like the S&P 500 and Dow Jones Industrial Average.
Home values have also been rising, further expanding American wealth and fueling household expenditures. The Federal Reserve estimates that as of the first quarter 2024, total American household wealth ripped past $151 trillion. To put that into perspective, just four years earlier, household wealth was sitting a bit below $104 trillion. In short, America remains embedded in a virtuous cycle in which household spending helps support growth demand for workers which in turn fuels more spending. Add to the mix massive outlays by tech companies on things like artificial intelligence (AI) platforms and ongoing federal spending on munitions, infrastructure, subsidies to expanding manufacturers, etc., and there remains plenty of aggregate demand powering the economy.
The Ghost of Milton Friedman
If one simply predicted economic outcomes by extrapolating current trends, there would be no reason for concern since the current trend is characterized by forward momentum. But there is this source of disquietude known as economic theory, which was designed by members of the dismal science, and which appears to have as its primary goal the destruction of confidence and certitude wherever and whenever it exists.
Some of these economists are monetarists, who are often among the brightest of the bunch. The godfather of this group is Milton Friedman while the godmother is Anna Schwartz. These brilliant minds liked to point out that monetary policy operates with long and variable lags. If that’s not disquieting, it’s unclear what could be.
What this means is that when interest rates rise, economic impacts do not transpire immediately. Rather, research indicates that it can require 18 months to two years or more for tighter monetary policy to have a material impact on the economy. As it turns out, the Federal Reserve began its rate hiking cycle on March 17, 2022. That was a bit more than two years ago. The reader will note the ominous portent of this insight. Much of the impact of higher interest rates could be in front of us. So, while the economy has been engaging in a soft landing, the ultimate landing may not be so soft.
Already, one can hear the rumblings of a less vibrant economy. For instance, the number of construction job openings fell sharply during a recent month as the number of construction starts declines. In June, industry job openings dipped by 71,000 to 295,000. Indeed, the pace of hiring among employers across all industries recently declined to multiyear lows. Leading indicators like residential building permits and fading architectural billings also hint at falling demand for construction services. The Associated Builders and Contractors Construction Backlog Indicator is 0.5 months lower than it was a year ago, sitting at 8.4 months. While the Federal Reserve will likely chip away at high interest rates during the months ahead, those rates will remain above rates to which economic actors had become accustomed, whether prospective homebuyers or owners of increasingly vacant office buildings.
In June, the latest month for which nonresidential construction data are available from the U.S. Census Bureau, nonresidential construction spending declined 0.2 percent not adjusting for inflation. Private construction spending declined 0.1 percent, an indication that those elevated interest rates have begun to take more of a bite out of industry momentum.
Looking Ahead
It would be easy to dismiss ramblings regarding an economic slowdown. After all, economists have been talking about such things for more than two years, and yet the economy has generally flourished. Many can and will also take comfort in upcoming interest rate reductions. The associated reason for optimism is obvious. If the economy has been able to handle higher interest rates thus far, undoubtedly it will be able to manage the lower interest rates to come. But many economists are pointing out that the Federal Reserve may already be too late to the game. While they gradually reduce interest rates, the U.S. economy could quickly decelerate, at least based on theoretical grounds if not on the most recent data releases, culminating in that long-predicted recession. Only time will tell.
More from Modular Advantage
From Model to Machine: Why Modular Scale Is Becoming a Software Problem, not a Material One
For modular manufacturers that have already secured demand and repeatable volume, the next major constraint may no longer be forming capacity itself. Increasingly, it is the continuity of the information feeding that capacity.
Who Will Define Modular Products for AI?
Artificial intelligence is making building configurators easier and less expensive to create. This makes urgent manufacturers’ need portable product definitions, stable identities, and shared interfaces regardless of how others’ software is produced.
From BIM to Robotic Production: A Digital Workflow for Customized Components in Volumetric Modular Construction
For volumetric modular manufacturers, the value of this workflow is not simply the use of robotics. Its real value is continuity.
Helping Build a Common Framework for Modular Construction in Canada
Canada’s modular construction sector continues to gain momentum, but scaling it successfully will depend on shared expectations across design, manufacturing, approvals, and project delivery. CSA Z251 helps provide that common foundation.
Edges, Exits & Equipment: A Modular Builder’s Guide to Rooftop Access
Rooftop access belongs in the factory design. Before the modules ship, the project team should identify each route’s users, confirm applicable requirements, coordinate with the roof system and structure, and assign responsibility.
When Timber Production and Modular Construction Share One System
As demand for multifamily and workforce housing continues to outpace what conventional construction timelines can deliver, models that reduce the number of handoffs between structural fabrication and modular assembly are likely to draw more attention.
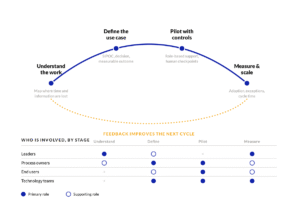
Your AI Strategy Is an Enablement Strategy
Tools will change. Teaching employees only the steps in one platform creates a narrow capability. Involving them in problem definition, process mapping, data assessment, controls, and measurement gives the organization a way to improve its systems as technology evolves.
By-Right Permitting: The Missing Lever for Scaling Modular Multifamily
Modular has already proven it can outperform traditional building methods on speed and cost per unit. The next frontier is outside the factory in the front end of the process, where projects either clear a path to construction or get stuck in review.
Remote Inspections and The Future of Factory Oversight
Remote inspection is becoming a practical part of modular construction oversight. Its value is greatest when it is used selectively, governed by clear procedures, and supported by complete traceability.
Reimagining Dry-In: How a Temporary-to-Permanent Roofing Strategy Mitigates Risk Between Modular Installation and Final Roof Construction
As volumetric modular projects continue to increase in scale and complexity, the Temporary-to-Permanent FiberTite Roof System represents an example of how traditional trade scopes can be reimagined through Design for Manufacturing and Assembly (DfMA) principles.