
Structural versus Cyclical: What Matters More?
Economic Transformation Meets the Business Cycle

Anirban Basu is the Chairman & CEO of Sage Policy Group and Chief Economist of the Modular Building Institute.
Leo Tolstoy’s acclaimed novel Anna Karenina opens with the famous line, “All happy families are alike; each unhappy family is unhappy in its own way.” Something similar can be said for the various segments that comprise the U.S. construction industry. Those segments that have dominated construction spending growth in recent years share a common feature – they benefit from dramatic economic transformations that generate a need to significantly alter the built environment. By contrast, segments that have not prospered generally have category-specific reasons for their malaise.
There are several structural transformations impacting the U.S. economy that stand to drive construction spending higher even if interest rates stay elevated for longer and the economy enters a mild recession. At the top of that list is construction related to manufacturing. For decades, supply chains were relocated from America to a bevy of nations offering lower wages, more relaxed regulatory environments, investment in supporting infrastructure, and rapidly expanding industrial workforces. The mantra among many American manufacturing CEOs appears to have been that as a profit maximizing enterprise, one must also be a cost minimizer, and minimizing costs means manufacturing beyond American boundaries.
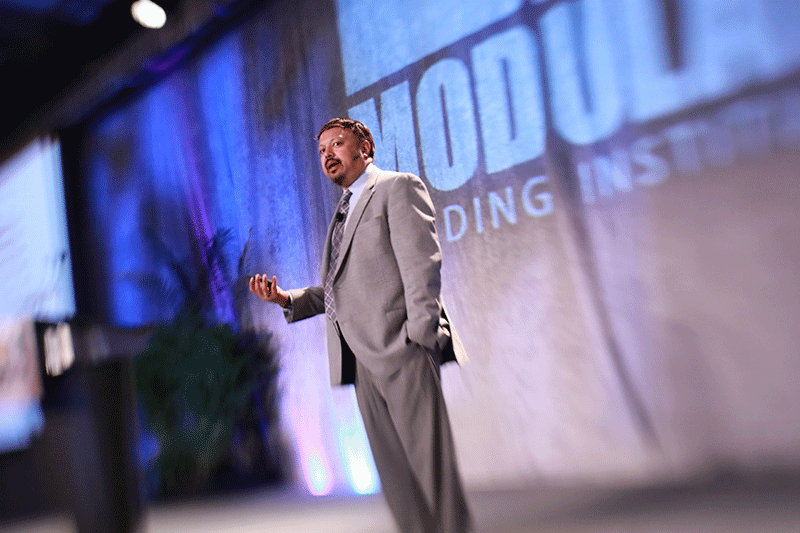
Anirban Basu speaks at the Modular Building Institute's annual World of Modular conference.
But now a new set of considerations have induced leaders of major global manufacturing enterprises to reconsider their site selection decisions. Among these are:
- a desire for simpler logistics emphasizing shorter transit distances and times;
- a need to better protect intellectual property;
- more reliable court systems;
- incentives offered by the USMCA, America’s trade deal with Canada and Mexico; and
- a recent set of subsidies offered under packages like the Chips and Science Act and the Inflation Reduction Act.
What’s more, certain advantages offered by other nations have been diminished by time. As indicated by Deloitte analysts, labor cost pressures in the U.S. and Western Europe “are being mitigated by advances in robotics and automation.” Meanwhile, Chinese wages have been ramping higher, increasing 83 percent over the past decade.
The impact on the U.S. construction industry has been nothing short of mind-bending. Between February 2020 and November 2023, total nonresidential construction spending in America expanded 29 percent (not adjusting for inflation). Meanwhile, construction spending in the manufacturing segment grew 168 percent.
Importantly, this is not a cyclical phenomenon. In fact, by one prominent measure (the Institute for Supply Management’s Purchasing Managers Index), the U.S. manufacturing sector had been in recession for 14 consecutive months through December 2023. Nonetheless, manufacturing related construction volumes have continued to edge skyward as structural factors predominate.
Structural factors are impacting several other segments as well. Among them are data centers, driven in part by the growing pervasiveness of artificial intelligence, healthcare facilities, supported by an aging population and rising healthcare utilization, and infrastructure, promoted by an abundance of federal support spawning from legislation passed in 2021.
According to CBRE, data center supply in primary markets expanded by nearly 492 megawatts or 12 percent during the first half of 2023 compared to the latter half of 2022. On a year-over-year basis, supply expanded by 19 percent. More data centers are on the way. According to the same source, “an all-time high of 2,287.6 MW was under construction in primary markets”, representing a 25 percent year-over-year increase.
For modular builders and other industry stakeholders, these structural dynamics are of consequence, or at least they should be. For the better part of two years, contractors and others involved in interest rate sensitive economic segments have fretted about the impact of higher rates and possible recession. At the time of this writing, interest rates are still high despite expectations that the Federal Reserve will begin to loosen monetary policy later in 2024 and in 2025. Risk of recession remains. But the structural transformations transpiring in the economy signify that some construction segments stand to continue to expand even if the U.S. economy enters a period of downturn at some point this year or next.
There are, of course, some real estate and construction segments that are negatively impacted by structural changes. Among these changes are the specter of remote work, business meetings conducted on various online platforms, and e-commerce. While e-commerce has helped spawn an industrial space boom in America as Amazon and others have developed a need for additional fulfillment center space, demand for shopping center space has been compromised. During the 1980s there were around 2,500 mall locations in America. By the early parts of the current decade, that figure had declined to around 700. A Wall Street Journal article quoted expert Nick Egelanian, president of retail consulting firm Site Works, who indicated that roughly a decade from now that figure could be down to 150. Such trends have obvious implications for retail construction.
Hotels catering to business travelers have also been impacted by newly emerging behaviors. Conducting business meetings, including the delivery of economic forecast presentations, via online platforms has become far more common. While leisure travel came back with a vengeance during the pandemic recovery period, business travel did not. Not coincidentally, among nonresidential construction’s sixteen segments, no segment has experienced as much spending decline as lodging.
And then there is the office market. This is a market that has also been negatively impacted by structural changes, and tends to suffer greatly during periods of recession. Despite U.S. economic and employment growth last year, the national office vacancy rate continued to rise. As lease renewals continue over the next several years, vacancy stands to climb. There is also a debt maturity wall, meaning that many building owners will have to refinance their debt into higher interest debt during the years ahead. In many instances, building owners are likely to hand their keys over to the bank as building valuations slip below balances owed. Among other things, that will translate into more difficult project financing for office space developers.
In the final analysis, modular builders will want to align themselves with relevant economic segments that stand to benefit from structural economic shifts. There are a few of them set to create prospective opportunities for contractors to support deal flow even if the broader economy enters its next downturn at some point in the near-term.
More from Modular Advantage
From Model to Machine: Why Modular Scale Is Becoming a Software Problem, not a Material One
For modular manufacturers that have already secured demand and repeatable volume, the next major constraint may no longer be forming capacity itself. Increasingly, it is the continuity of the information feeding that capacity.
Who Will Define Modular Products for AI?
Artificial intelligence is making building configurators easier and less expensive to create. This makes urgent manufacturers’ need portable product definitions, stable identities, and shared interfaces regardless of how others’ software is produced.
From BIM to Robotic Production: A Digital Workflow for Customized Components in Volumetric Modular Construction
For volumetric modular manufacturers, the value of this workflow is not simply the use of robotics. Its real value is continuity.
Helping Build a Common Framework for Modular Construction in Canada
Canada’s modular construction sector continues to gain momentum, but scaling it successfully will depend on shared expectations across design, manufacturing, approvals, and project delivery. CSA Z251 helps provide that common foundation.
Edges, Exits & Equipment: A Modular Builder’s Guide to Rooftop Access
Rooftop access belongs in the factory design. Before the modules ship, the project team should identify each route’s users, confirm applicable requirements, coordinate with the roof system and structure, and assign responsibility.
When Timber Production and Modular Construction Share One System
As demand for multifamily and workforce housing continues to outpace what conventional construction timelines can deliver, models that reduce the number of handoffs between structural fabrication and modular assembly are likely to draw more attention.
Your AI Strategy Is an Enablement Strategy
Tools will change. Teaching employees only the steps in one platform creates a narrow capability. Involving them in problem definition, process mapping, data assessment, controls, and measurement gives the organization a way to improve its systems as technology evolves.
By-Right Permitting: The Missing Lever for Scaling Modular Multifamily
Modular has already proven it can outperform traditional building methods on speed and cost per unit. The next frontier is outside the factory in the front end of the process, where projects either clear a path to construction or get stuck in review.
Remote Inspections and The Future of Factory Oversight
Remote inspection is becoming a practical part of modular construction oversight. Its value is greatest when it is used selectively, governed by clear procedures, and supported by complete traceability.
Reimagining Dry-In: How a Temporary-to-Permanent Roofing Strategy Mitigates Risk Between Modular Installation and Final Roof Construction
As volumetric modular projects continue to increase in scale and complexity, the Temporary-to-Permanent FiberTite Roof System represents an example of how traditional trade scopes can be reimagined through Design for Manufacturing and Assembly (DfMA) principles.