Navigating Risk in Commercial Real Estate and Modular Construction: Insights from a 44-Year Industry Veteran
A Legacy in Risk Management
Daniel Seltzer’s grandfather and father founded a risk management/insurance brokerage in Philadelphia in the 1920s, establishing the foundation for what would become his lifelong career. Over the span of 44 years, he’s built a distinguished path in insurance and risk advising, holding the CPCU.
Early in his career, Seltzer gained early underwriting experience during eighteen months “running slips” at Lloyd’s of London. He later returned to the family firm, where he climbed to President and CEO before its sale in 2013, and continued his career with a respected company in the field. Eighteen months ago, he joined RCM&D—a firm he has admired since childhood. For Seltzer, it was coming home again.
Founded in 1885, RCM&D (platform company of Unison Risk Advisors), employs roughly 1,600 people, all of whom share ownership in the privately controlled company.
Defining the Management of Risk in Real Estate Development
Seltzer categorizes real estate development risk into three primary types:
- Stabilized Assets – Completed buildings where operational risk management is key, such as ensuring protective systems—sprinklers, surveillance, and life-safety components—are functioning properly.
- Development Projects – Buildings under construction, where well-crafted insurance programs and strong indemnification requirements for general contractors and subcontractors are essential, including optimal Additional Insured endorsements and precise contractual language.
- Corporate Risk – Directors and Officers or General Partnership Liability, requiring careful evaluation of exposures and selection of appropriate limits and retentions to protect the balance sheet.
Modular vs. Traditional Construction: A Risk Perspective
Seltzer explains that although modular construction differs quite a bit from traditional projects, the risk management process itself does not change. “Step one, risk identification, followed by quantifying the range of financial impact of such risk. The advisor must then recommend the method(s) for managing risk,” he says.
The five fundamental strategies remain: avoidance, reduction, control, transfer, and assumption. Where modular and traditional construction diverge is in the type and intensity of certain risks.
Risks Modular Construction Reduces
Modular construction shortens the period of outdoor work which significantly reduces:
- Public and worker injury risk
- Weather-related damage
- Construction defect likelihood, due in part to more robust upfront engineering
Risks Modular Construction Amplifies
At the same time, modular introduces unique and amplified risks:
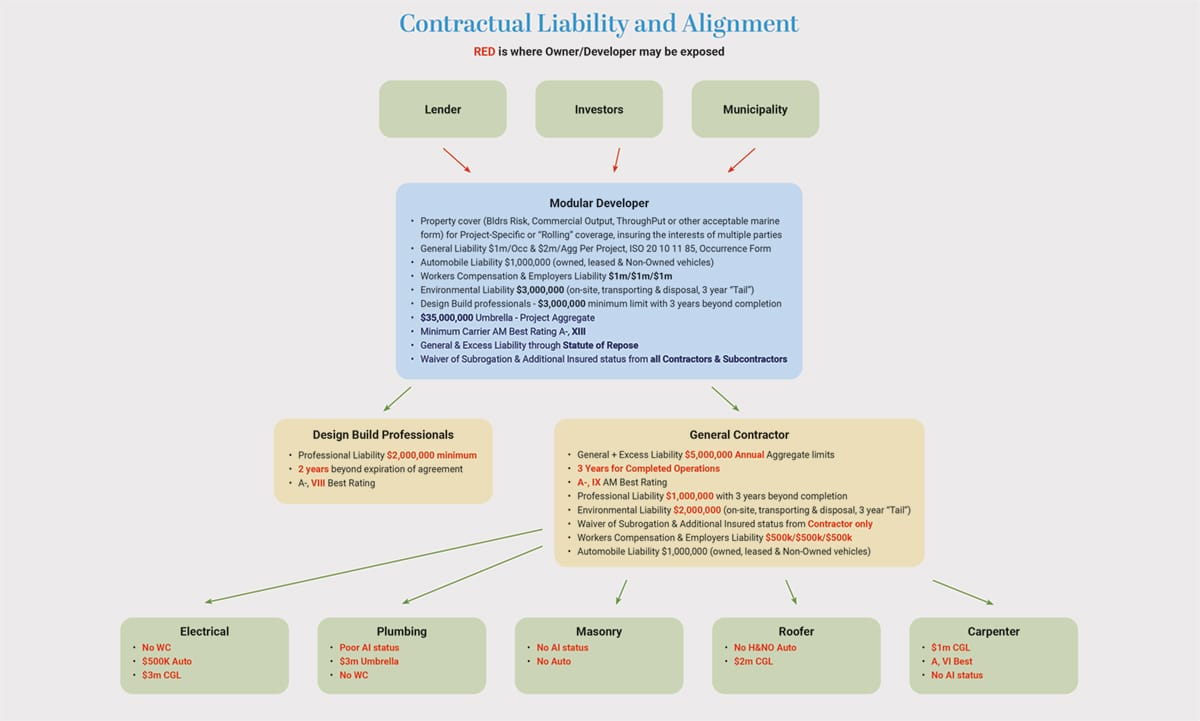
- Transportation risk– Usually, more parties are involved in the development, transit logistics are more complex, and storage and/or consolidation points increase. The risk advisor should assess the values and various parties in the mix, study the Gantt/CPM, and make recommendations to the developer.
- “Zipping” risk– The on-site joining of modular units—creates a sequencing risk unique to modular builds.
Why Modularity Challenges Insurers
Seltzer calls modular construction a “relative newcomer” to insurers because the industry lacks the actuarial history needed for accurate pricing. Until modular generates enough credible loss data, carriers often blend its results with traditional construction.
To illustrate the insurance challenge, Seltzer poses a thought-provoking comparison: “In what other industry does the provider of the product or service not know their ultimate costs until years after the sale is made? Insurance carriers do not know their costs until years after the premium is charged.”
Still, he stresses that insurance for modular construction is readily available. The issue is not accessibility but accuracy of long-term modeling.
Mapping Risk Across Modular Project Phases
Modular projects involve manufacturing, transportation, and on-site assembly. Developers must understand exactly what they are responsible for versus what they subcontract. Risk advisors should research the developer’s contractors, subcontractors, and design-build consultants—especially the modular manufacturer.
“If my client is a developer and they’re going to hire A-B-C manufacturer, it's very important to research that firm to help assess what the risk is,” Seltzer explains.
The Top Three Risk Pitfalls for Modular Developers
- Underinvesting Time in Risk Planning – Developers often under-allocate time to the risk management process.
- Errors & Omissions (Professional Liability) Risk – Modular projects involve many consultants. Developers commonly require these partners to carry professional liability insurance, but Seltzer recommends an additional layer be considered: OPPI (Owner’s Protective Professional Indemnity) coverage.
- Disjointed Property Insurance – Modular projects include multiple risk locations: manufacturing facilities, transit routes, temporary storage, project-site staging areas, and installation zones. Seltzer strongly recommends a single inland marine policy, covering transit, off-site storage, temporary housing, and builder’s risk under one program.
Choosing the Right Broker
With over 35,000 insurance brokers in the U.S., Seltzer suggests a deliberate and thorough process in advance of hiring your risk advisor, similar to that of a doctor and tax advisor. He emphasizes that the right broker should:
- Arrive prepared and ask insightful questions
- Review all contracts
- Visit the project site
- Produce professional-quality submissions
- Understand modular construction deeply
“A broker who does not meet these criteria may leave the developer with gaps revealed only when it’s too late,” he cautions.
For Seltzer, transparency isn’t a courtesy—it’s a safeguard. “Developers should always see exactly what the broker submits to the market and the underwriters’ written responses,” he says. This level of visibility is rare but essential, as a single omitted detail can cascade into costly exposures.
Business Interruption and Real Loss Scenarios
Seltzer distinguishes between Loss of Income, which covers the loss of net income and continuing expenses, and Extra Expense, which covers the post-loss incremental increase of costs required to minimize loss. “Coverage must reflect the actual project architecture, supply chain, and lender requirements—not a generic template,” he says, offering real scenarios he sees often to illustrate the stakes, including:
- Flood at the manufacturing plant destroys modules, causing a two-month delay.
- Fire two weeks before the issuance of the Certificate of Occupancy halts progress and increases interest expenses.
Trucking consolidation turns a $50,000-per-truck exposure into $400,000 in one location.
Professional Liability: Retroactive Dates and Project vs. Practice Policies
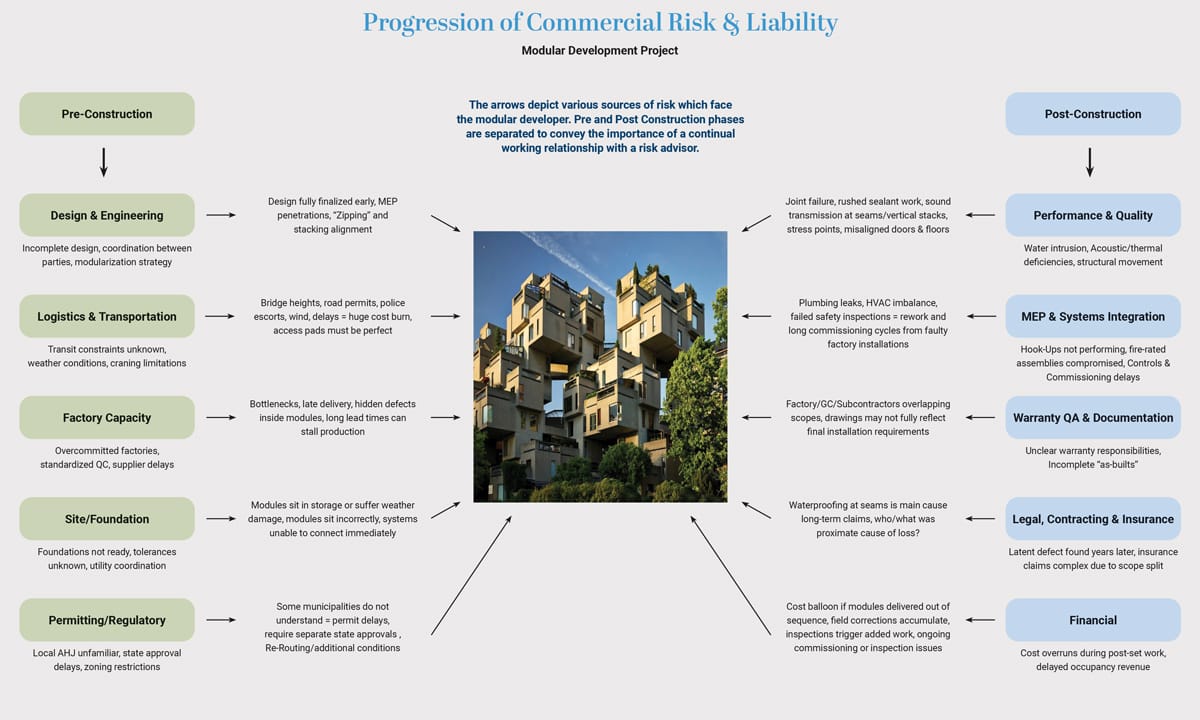
Seltzer demystifies Claims Made Professional Liability insurance: a retroactive date defines how far back claims-made coverage applies. “For example, May 1st, 2018 - a $1 million limit applies to all projects since that date—not a single customer and not a single year. Most policies are Practice-based, covering the consultant’s entire practice, while Per-Project policies are not seen as often and are more expensive, though far clearer,” he notes.
Managing Risk in Transit and Storage
Developers frequently rely on fragmented coverage placed by several different parties, including manufacturer, transporter, freight forwarded, supplier, and warehouse owner. Seltzer’s solution: a consolidated property program (inland marine policy), ensuring all parties’ interests are covered as the material moves from the first time by the supplier to the last time when delivered to the project site since the developer/owner pays 100% of all costs.
“Fragmented programs lead to finger-pointing, lengthy subrogation, and costly disputes,” he states.
Cyber Risks: The Silent Threat
Additionally, Seltzer flags two cyber threats:
- Social engineering – Fraudulent payment requests and spoofed emails. SOPs requiring verbal confirmation before wiring funds mitigate risk.
- Ransomware – Malicious actors lock systems until ransom is paid, potentially crippling operations.
“Cyber Insurance exists but must be carefully structured, as coverage varies from one carrier to the next, and given the nature of this risk, often the insuring agreement is not keeping up with the times,” explains Seltzer.
Why Professional Liability (aka E&O) is the “Wild West”
Unlike per state statutory workers’ compensation, professional liability is highly customized. “Just because someone buys professional liability doesn’t mean it’s done correctly,” Seltzer warns. Customization requires experienced guidance—otherwise, developers assume risk unknowingly.
Front-End Planning and Contract Structure
Seltzer says that front-end planning is where risk—and opportunity—resides. “Developers who engage deeply in the process can materially reduce ‘Total Cost of Risk’ or TCOR.”
Contracts should hold the party performing work financially responsible, with indemnification for others, and name the developer as an additional insured (excluding workers’ comp and professional liability). But additional insured coverage is nuanced. “Over 100 endorsements exist, and many only cover work during active operations, not during the statute of repose,” Seltzer notes.
Evaluating Modular Suppliers and Closing Coverage Gaps
Developers must examine suppliers’ schedules, financial stability, and backup plans. Seltzer recommends:
- Reviewing proposed Gantt charts or CPM schedules
- Considering performance, supply, or completion bonds
- Negotiating reciprocity agreements for alternate manufacturing
Coverage gaps often appear in transportation, additional insured endorsements, professional liability, and builder’s risk. Choosing the right advisor is critical. Risk is rarely mishandled because developers don’t care, but because they may trust an insurance broker with little to no modular expertise
Surround Yourself with Experts
Finally, Seltzer emphasizes that risk evolves. “Surrounding yourself with really well-intended experts is the best way. And run it as a business. Insurance decisions should be intentional, dynamic, and continuously reassessed. Don’t just buy insurance from the same person you’ve always bought from. Risk is dynamic, and that can create risk. Have an advisor that stays involved and asks good questions.”
If you’re looking for a risk advisor with deep industry insight and a hands-on, analytical approach, connect with Daniel Seltzer at RCM&D at dseltzer@rcmd.com or 800-346-4075.
About the Author: John McMullen, PCM, is the marketing director for the Modular Building Institute. You can reach him directly at mcmullen@modular.org or on LinkedIn.
More from Modular Advantage
Mind the Gap: The Interface Between Onsite and Offsite Construction
Every design for manufacture and assembly (DfMA) project — modular, mass timber, or panelized — is really two projects joined at a seam. One is built in a controlled factory to millimeter tolerances; the other in the field, in weather, to the looser tolerances of poured concrete and human hands. Between them sits an interface: where the factory’s precision meets the site’s reality.
Rules, Rails & Repeatability: Applying DfMA to Modular Healthcare
DfMA offers several advantages for healthcare projects, with faster delivery among the most valuable. Schedule matters when building new facilities, expanding campuses, renovating existing space or bringing care closer to communities that need it.
Precision and Possibility: Demands of DfMA and What Modular Mass Timber Makes Possible
Mass timber does not automatically create an efficient modular building. Its precision makes early coordination more important: fabricated components will accurately reproduce both the team’s solutions and its mistakes. The material’s advantages are realized only when supported by an equally precise design and delivery process.
Catch It in the Factory, Not in the Field: Smarter Testing for Modular Builds
Integrating watertightness and airtightness testing into factory workflows transforms quality assurance from a reactive process into a proactive commissioning strategy. It ensures that every module shipped is field ready and resilient for transportation while also supporting the ability of the modular construction industry to make buildings better.
Modular Construction Contracts: Key Considerations for Successful Canadian Projects
Starting a modular project with a well-developed contract protects both the owner and the contractor. It will help keep the project on track and on budget, and it will improve quality from the factory floor to final installation on-site.
Modular by Design: Turning Architecture into a Manufacturing System
Modular construction is often presented as a faster way to build. Speed, however, is only one part of its value. The larger opportunity is to create a coordinated design and production system that improves quality, reduces uncertainty, and allows a building to move efficiently from concept design through manufacturing, transportation, installation, and completion.
Repeatability Begins with Trust: What Alora at Dry Creek Reveals About Scaling Modular Housing
Alora at Dry Creek, a 329-unit, multifamily community comprising five four-story buildings in Centennial, Colorado, demonstrates how repeatable design, standardized manufacturing and early collaboration can work together to create a model that is not only faster to deliver, but easier to replicate across future projects.
T.R. Arnold: The Art of Third-Party Inspections
T.R. Arnold (TRA), a third-party inspection company in Elkhart, Indiana, contracts with modular manufacturers across the US. Manufacturers register with each state to which they intend to send their modules and may be required to hire a third-party inspection company.
Creating an ‘Ecosystem for Innovation:’ 50+ Years of Modular Construction Oversight in Virginia
Virginia’s modular building program began in 1973, with the implementation of the Virginia Industrialized Building Unit and Mobile Home Safety Regulations. Now it’s leading the country in modular code adoption.
Understanding Thermal Barriers Compliance Methods & Emerging NFPA-275 Foam Plastic Technologies
New fire barrier technologies are improving total costs and margins in major areas of construction, such as commercial, government, union and prevailing wage projects. These benefits translate into other large fringe areas, such as agriculture, commercial cold storage facilities, grow houses, outbuildings, military and aviation hangars.